Experian Boost: what it counts, what it doesn't, and who sees it.
Boost is free and takes one sitting. Used right, it puts bills you already pay on your Experian file. Used without a plan, it changes a file the lender may never look at.
Experian Boost is a free tool that lets you add certain bills you already pay to your Experian credit file. You connect the bank account the bills are paid from, choose which payments to add, and Experian adds the on-time history.
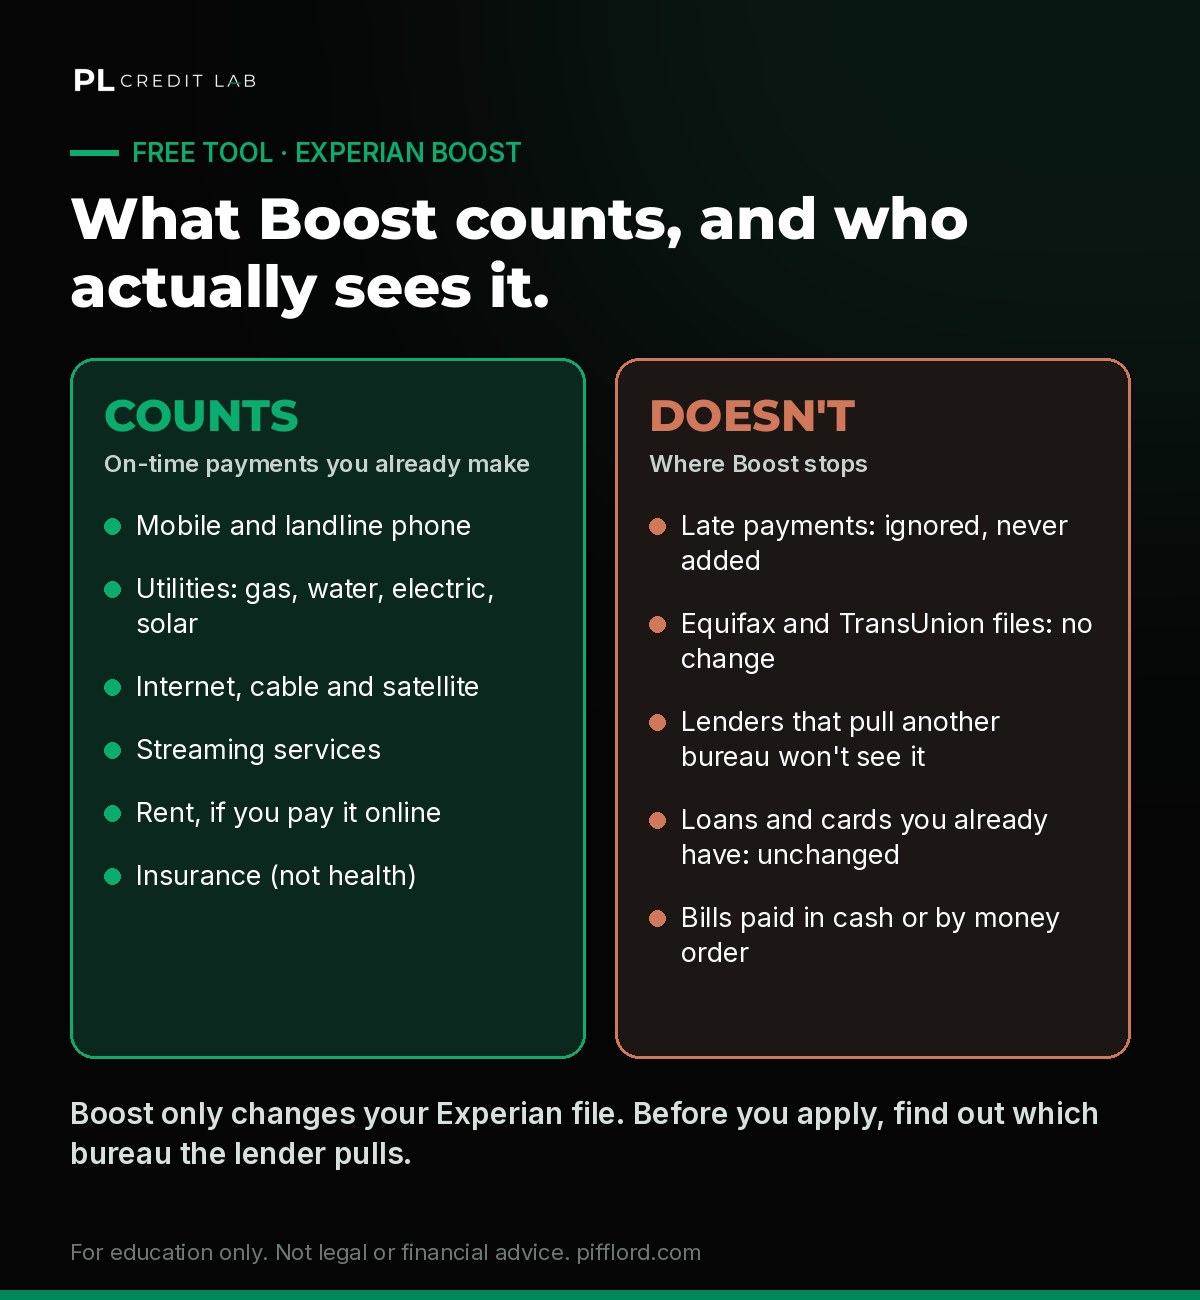
Boost counts on-time payments only, and only on your Experian file.
What it counts
- Mobile and landline phone
- Utilities: gas, water, electricity and solar
- Internet, cable and satellite
- Streaming services
- Insurance, other than health
- Residential rent, if you pay it online
Only on-time payments are added. Experian says late payments are ignored, so adding a bill can't lower your FICO Score through Boost.
What it doesn't do
- It only changes your Experian file. Equifax and TransUnion don't receive Boost data. A lender that pulls one of those bureaus will not see it.
- It applies to specific score versions. Experian lists FICO Scores 3, 8, 9 and 10 and VantageScore 3 and 4. Mortgage lenders often use older score versions that aren't on that list.
- It only sees payments it can find. Bills paid in cash or by money order won't show up in your bank data.
How to set it up
- Create a free Experian account (no paid plan required).
- Connect the bank account or card you pay your bills from.
- Review the bills Experian finds and choose which ones to add.
- Check your Experian report afterward to confirm what was added.
- Your Experian file is thin, with few accounts or a short history.
- You are about to apply with a lender you know pulls Experian.
- You pay phone, utility or streaming bills on time from a bank account you can connect.
Boost vs. other ways to add payment history
- Rent reporting services send your rent history to one or more bureaus. Some charge a fee; check which bureaus they report to before you pay.
- Credit builder loans create a new installment account that reports to the bureaus as you make payments. They cost interest or fees, so read the terms.
- Secured cards report to the bureaus like a regular card. Keeping utilization low and paying on time builds history on every bureau the issuer reports to.
Boost is the only one of these that is free and adds bills you already pay, which is why it's a good first step. It just isn't the whole plan.
Know the bureau before you apply
Boost works best as part of a plan: know which bureau a lender pulls, then make sure that file is accurate and complete. Our free Boost Playbook walks through it step by step, and the 8-File Audit shows you every file lenders read.
For educational purposes only. Not legal or financial advice. PL Credit Lab is a brand of PIFFLORD LLC and is not a credit repair organization, law firm or lender. No score, deletion, approval, funding amount or timeline is promised. You can dispute inaccurate information with the credit bureaus yourself at no cost.
Common questions.
Is Experian Boost free?
Yes. You need a free Experian account; connecting your bank accounts costs nothing.
Can Experian Boost hurt my score?
Experian says Boost only adds on-time payments and ignores late ones, so it can't lower your FICO Score through Boost.
Does Boost help with Equifax or TransUnion?
No. Boost data goes only into your Experian file.
Can I remove bills later?
Yes. You choose which bills to add and can change that or disconnect your accounts at any time.
Put the bills you already pay to work.
The Experian Boost Playbook
Set it up the right way in one sitting, and know when it helps.
Get the free guideThe Secured Card Blueprint
Boost covers one bureau. Here's how to start on all three.
Get it for $7The 8-File Audit
Every file lenders read about you, and how to get each one free.
Get the free guide