True 0% APR vs. deferred interest: same 0%, very different ending.
Both offers say 0%. The difference shows up on the last day of the promotion, and it can be hundreds of dollars.
A true 0% intro APR means no interest is charged during the promotional period. If a balance is left when it ends, interest starts on that remaining balance from that day forward.
Deferred interest means interest is building in the background the whole time. If you pay the full promotional balance before the deadline, it's waived. If any amount is left, the interest from the original purchase date is added to your balance at once.
Same purchase, same payments, very different ending.
The math, on one example
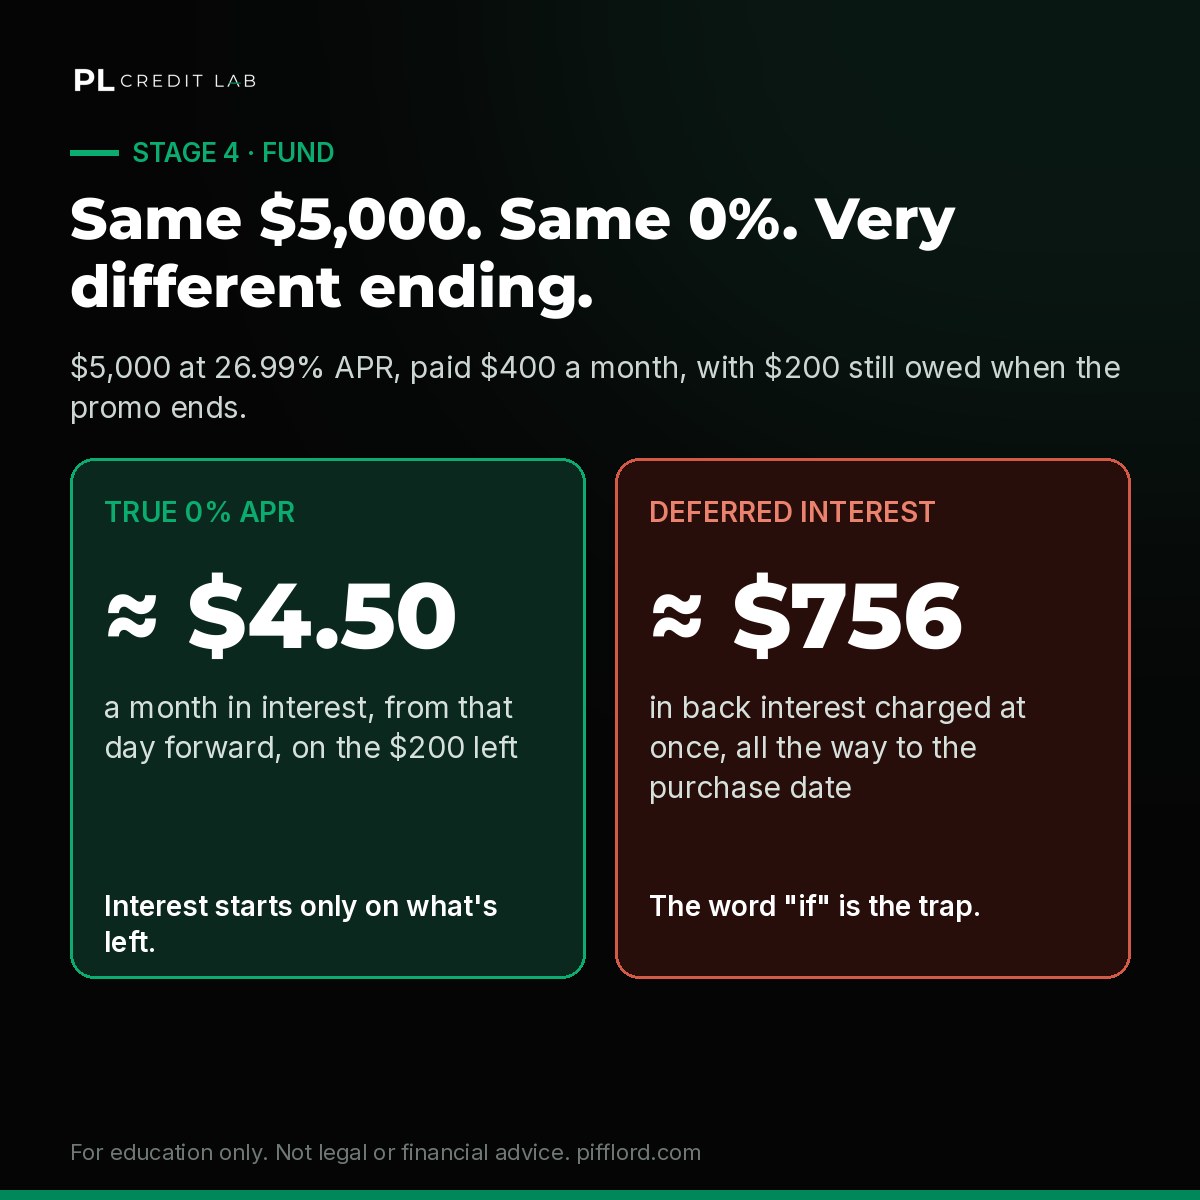
Say you put $5,000 on a 12-month promotion at a 26.99% standard APR and pay $400 a month. After 12 payments you've paid $4,800, so $200 is left.
- True 0% APR: interest starts on the $200 left, about $4.50 a month at 26.99%.
- Deferred interest: the interest that built up on the declining balance over all 12 months, about $756, is charged at once.
Same purchase, same payments. The only difference is one word in the offer.
The payment that actually clears it
To clear $5,000 in 12 months, the payment is $5,000 ÷ 12 = about $417 a month, not $400. That $17 a month is the difference between $0 in promotional interest and about $756 on a deferred-interest offer. On a true 0% offer, the same shortfall costs a few dollars a month after the promotion ends.
- $5,000 over 12 months: about $417 a month
- $5,000 over 15 months: about $334 a month
- $5,000 over 18 months: about $278 a month
- $5,000 over 21 months: about $239 a month
Set that number as an automatic payment the day you make the purchase. The minimum payment on the statement is usually far lower and is not designed to clear the balance in time.
How to tell which one you have
- "0% intro APR for 12 months" usually means a true 0% promotion.
- "No interest if paid in full within 12 months" means deferred interest. The word "if" is the trap.
- Check the card agreement and the promotional terms. For a deferred-interest promotion, your statement must show the date the balance has to be paid in full to avoid the interest.
How payments are applied
Under the CARD Act rules in Regulation Z (12 C.F.R. § 1026.53), payments above the minimum generally go to the balance with the highest APR first. For deferred-interest balances there is an exception: in the last two billing cycles before the promotion ends, the excess goes to the deferred-interest balance first. You can also ask the issuer to apply excess payments to that balance sooner.
- Find out whether it's a true 0% APR or deferred interest.
- Divide the balance by the number of months to get the payment that clears it in time.
- Set that payment up as an automatic payment, not the minimum.
- Write down the end date and check your balance two statements before it.
Stage 4 of our method, Fund, works through this math with a worksheet before you use the money. No manufactured spend, and no shortcuts that put an account at risk.
For educational purposes only. Not legal or financial advice. PL Credit Lab is a brand of PIFFLORD LLC and is not a credit repair organization, law firm or lender. No score, deletion, approval, funding amount or timeline is promised. You can dispute inaccurate information with the credit bureaus yourself at no cost.
Common questions.
Is deferred interest the same as 0% APR?
No. A true 0% APR charges no interest during the promotion. Deferred interest charges all of it back to the purchase date if any of the promotional balance is left when it ends.
How do I avoid deferred interest charges?
Pay the full promotional balance before the deadline. Divide the balance by the number of months and pay at least that amount each month.
Where do I find which kind of offer I have?
In the promotional terms and your card agreement. For a deferred-interest promotion, each statement must show the date the balance has to be paid in full to avoid the interest.
Do extra payments go to the promotional balance?
Generally, amounts above the minimum go to the highest-APR balance first, except in the last two billing cycles of a deferred-interest promotion. You can ask the issuer to apply them to the deferred balance sooner.
Do the math before you sign.
Fund
Readiness check, offer math, lender audit, payoff plan and the Fund Gate checklist.
Get Part 4 for $40All four parts
Repair, Establish, Build and Fund in one edition, with every workbook.
Get the Complete EditionYour file, checked
Upload your reports and get a one-page snapshot with your next three steps.
Get my free review